2026 Charitable Donation Deduction: What Non-Itemizers Should Know
The 2026 charitable donation deduction gives many people who do not itemize a new reason to keep their giving records. As holiday appeals arrive, review which gifts qualify before assuming every donation will reduce your federal tax bill.
For eligible taxpayers, the new rule applies to qualifying cash contributions made during 2026 and claimed on a 2026 return filed in 2027. It is current law, rather than a proposed change. Here is what families in San Marcos, Kyle, Buda, New Braunfels and Wimberley should know.
What Is the 2026 Charitable Donation Deduction?
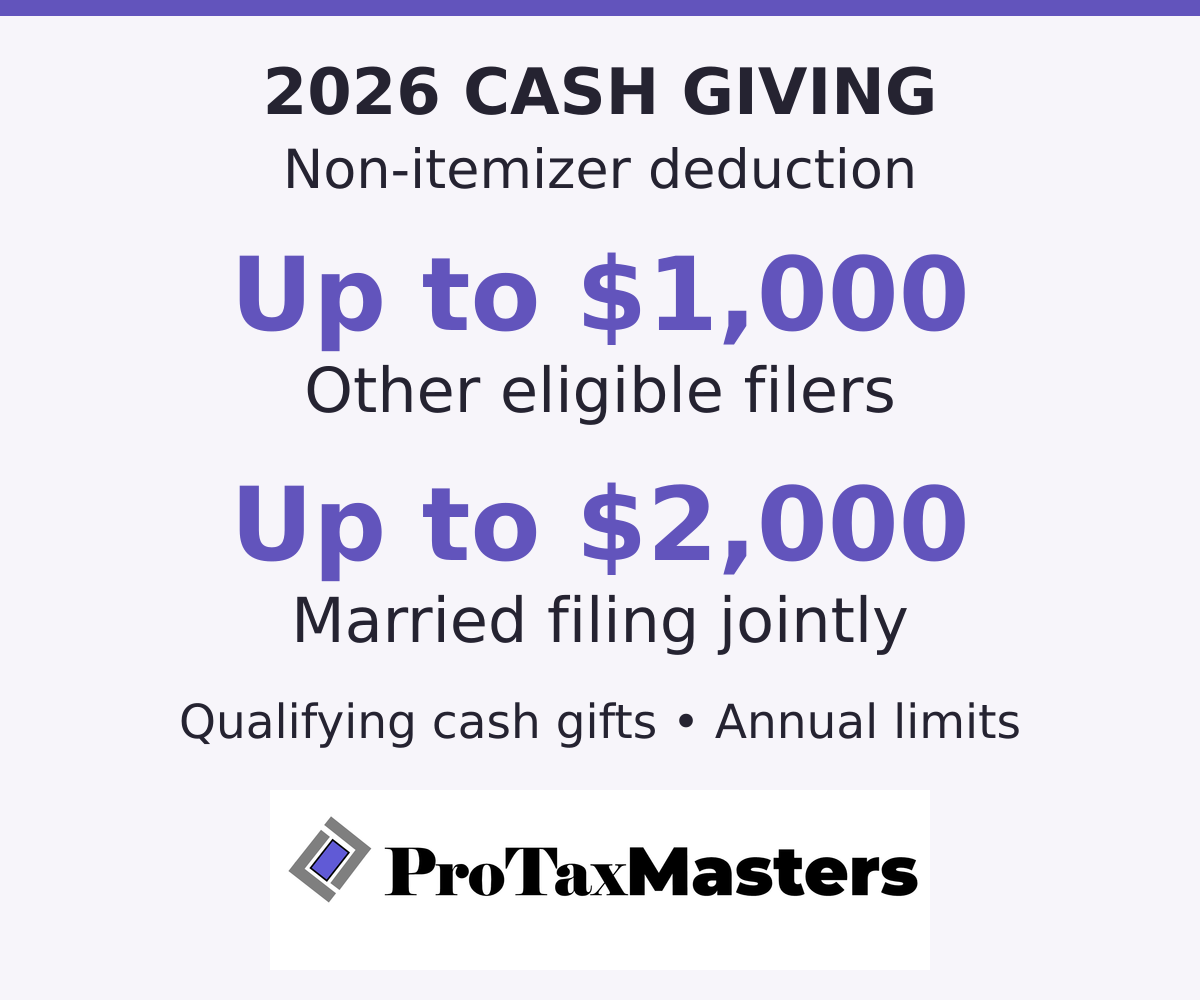
The IRS explains in Publication 6196 that eligible taxpayers who do not itemize may deduct up to $1,000 in qualifying cash contributions, or $2,000 for married taxpayers filing jointly. This can benefit people who take the standard deduction.
Those amounts are annual limits per return, not per charity. You still need eligible contributions and supporting records; the deduction is not automatic.
A deduction reduces taxable income. It does not provide a dollar-for-dollar tax credit or guarantee a refund. As a simplified illustration, a fully allowable $1,000 deduction would reduce federal income tax by $220 if the entire deduction offsets income taxed at 22%. Your actual result depends on your return.
Which Donations Should You Review?
This particular deduction is for qualifying cash or monetary gifts. Checks, credit-card payments and electronic transfers can be monetary contributions. Donated clothing, household goods and other property do not count toward this cash-only deduction.
The recipient matters, too. The IRS donation recordkeeping guidance explains that gifts to individuals, including personal fundraising accounts, are not deductible charitable contributions. A worthy cause does not by itself establish tax eligibility.
Use the IRS Tax Exempt Organization Search to check an organization’s eligibility. Certain eligible churches and organizations covered by group exemptions may not appear separately, so a missing search result needs further review. Donations to donor-advised funds generally do not qualify for this non-itemizer deduction.
Keep Records for Every Monetary Gift
Save a bank record or written communication from the charity showing its name, the contribution date and the amount. Store electronic receipts in a dedicated 2026 donation folder so they are ready at filing time.
For each contribution of $250 or more, obtain a contemporaneous written acknowledgment from the charity. A bank statement alone is insufficient. The acknowledgment must address whether you received goods or services and, when applicable, describe them and estimate their value.
Under the recordkeeping rules in IRS Publication 526, you must receive that acknowledgment by the earlier of the date you file or the return’s due date, including extensions. Separate gifts generally are not combined to determine the $250 threshold. Publication 526 currently covers 2025; use the IRS’s 2026 guidance for the new deduction limits.
What If You Itemize?
Itemizers follow different rules. IRS Publication 505 for 2026 explains that an individual’s itemized charitable deduction is subject to a new floor: contributions must exceed 0.5% of adjusted gross income. Other limits may also apply.
For example, at $100,000 of adjusted gross income, the floor is $500. With $2,000 of otherwise eligible contributions, $1,500 remains after applying that floor, before other applicable limitations. This example does not determine whether itemizing produces a better overall result.
Make Giving Records Part of Your Tax Preparation
Before you file, gather your donation receipts, charity acknowledgments and payment records. Separate monetary gifts from property donations, and flag any payment involving a dinner, event ticket or other benefit for review.
Our year-end tax planning checklist can also help business owners organize the rest of their records.
Michael J. Garcia, EA (Enrolled Agent), at ProTaxMasters LLC, can help you review how your contributions fit your individual return. We serve Central Texas and remote clients.
Visit ProTaxMasters.com to arrange your complimentary 30-minute initial consultation, or email team@protaxmasters.com.
This article provides general tax information and is not individualized tax advice. Tax obligations and planning opportunities depend on your facts and circumstances.